A car accident tends to raise questions faster than anyone can answer them. Who pays the medical bills? What do you say to the insurance company? Is that first offer worth taking? We hear these concerns all the time, and they make complete sense when your life has just been turned upside down.
Most people have never dealt with an injury claim before, so there’s no reason they should know how the process works. Our friends at Schmittgens Injury Law Firm discuss several of the concerns people bring to a car accident lawyer in the days and weeks after a wreck. Below are some of the questions we’re asked most often, with straightforward answers.
Should I See a Doctor If I Don’t Feel Hurt?
Yes. Please do.
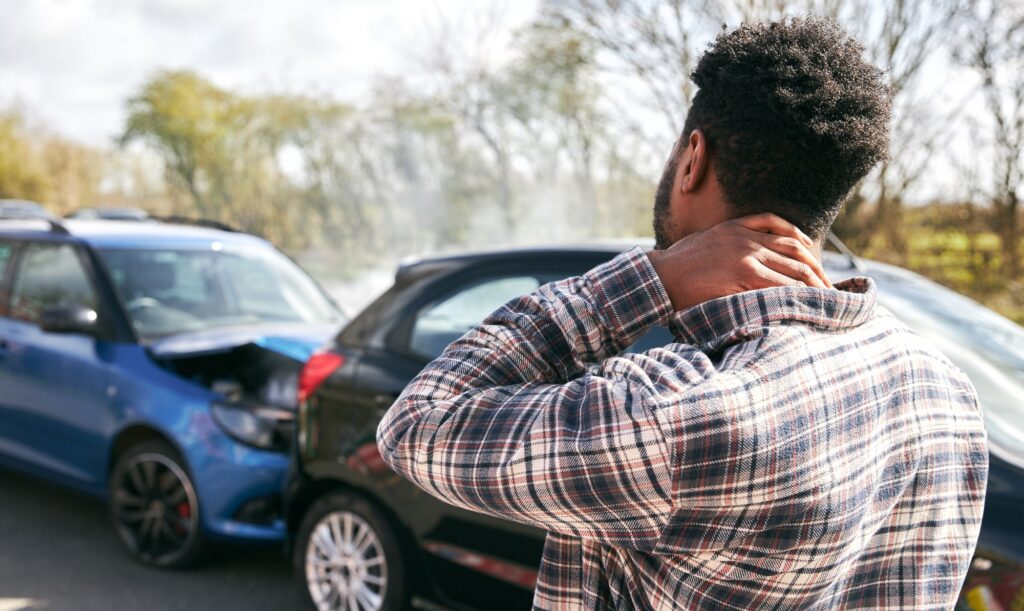
Adrenaline can hide pain for hours or even days after a crash. Whiplash, concussions, and back injuries are known for showing up late. Getting evaluated quickly protects your health, and it also creates a record linking your injuries to the accident. When someone waits weeks to see a doctor, insurers often argue the injury came from something else.
What Should I Say to the Insurance Adjuster?
Less than you might think. Adjusters are often friendly and easy to talk to, and that’s part of the job. Their role, though, is to limit what the insurance company pays.
You can give basic information like your name, contact details, and the date of the accident. Be careful about guessing at fault, describing your injuries before you know their full extent, or agreeing to a recorded statement with the other driver’s insurer. If you’re unsure, it’s reasonable to say you’d like to speak with an attorney first.
Is the First Settlement Offer Usually Fair?
Sometimes it is. Often, it’s not.
Early offers tend to come before anyone knows how long recovery will take or what treatment you’ll need down the road. Once you accept and sign a release, you generally can’t go back and ask for more, even if your condition gets worse. We always encourage people to understand the full picture before agreeing to anything.
What Kinds of Losses Can Be Part of a Claim?
People are sometimes surprised by how much a claim can cover. Depending on the facts, it may include:
- Medical bills, both current and future
- Lost wages and reduced ability to earn
- Vehicle repair or replacement
- Pain, suffering, and loss of enjoyment of life
Keep receipts, bills, pay stubs, and notes about how your injuries affect your day. Those small details add up and help tell your story.
What If the Other Driver Doesn’t Have Insurance?
This happens more than people expect, and it’s understandably stressful. But it doesn’t always mean you’re out of luck. Your own auto policy may include uninsured or underinsured motorist coverage, which can step in when the at-fault driver can’t pay. Many people carry it without realizing it. Pull out your policy or call your agent to see what you have.
When Does It Make Sense to Talk With a Lawyer?
There’s no single rule. A minor fender bender with no injuries may be easy to handle on your own. But if you’ve been hurt, if fault is disputed, or if the insurance company is delaying or denying your claim, getting guidance early can make a real difference. Evidence fades and memories blur, and it’s much easier to protect a claim at the start than to repair one later.
If you’ve been injured in a car accident and have questions about your situation, we encourage you to connect with an attorney who can walk you through your options and help you decide on the best path forward.